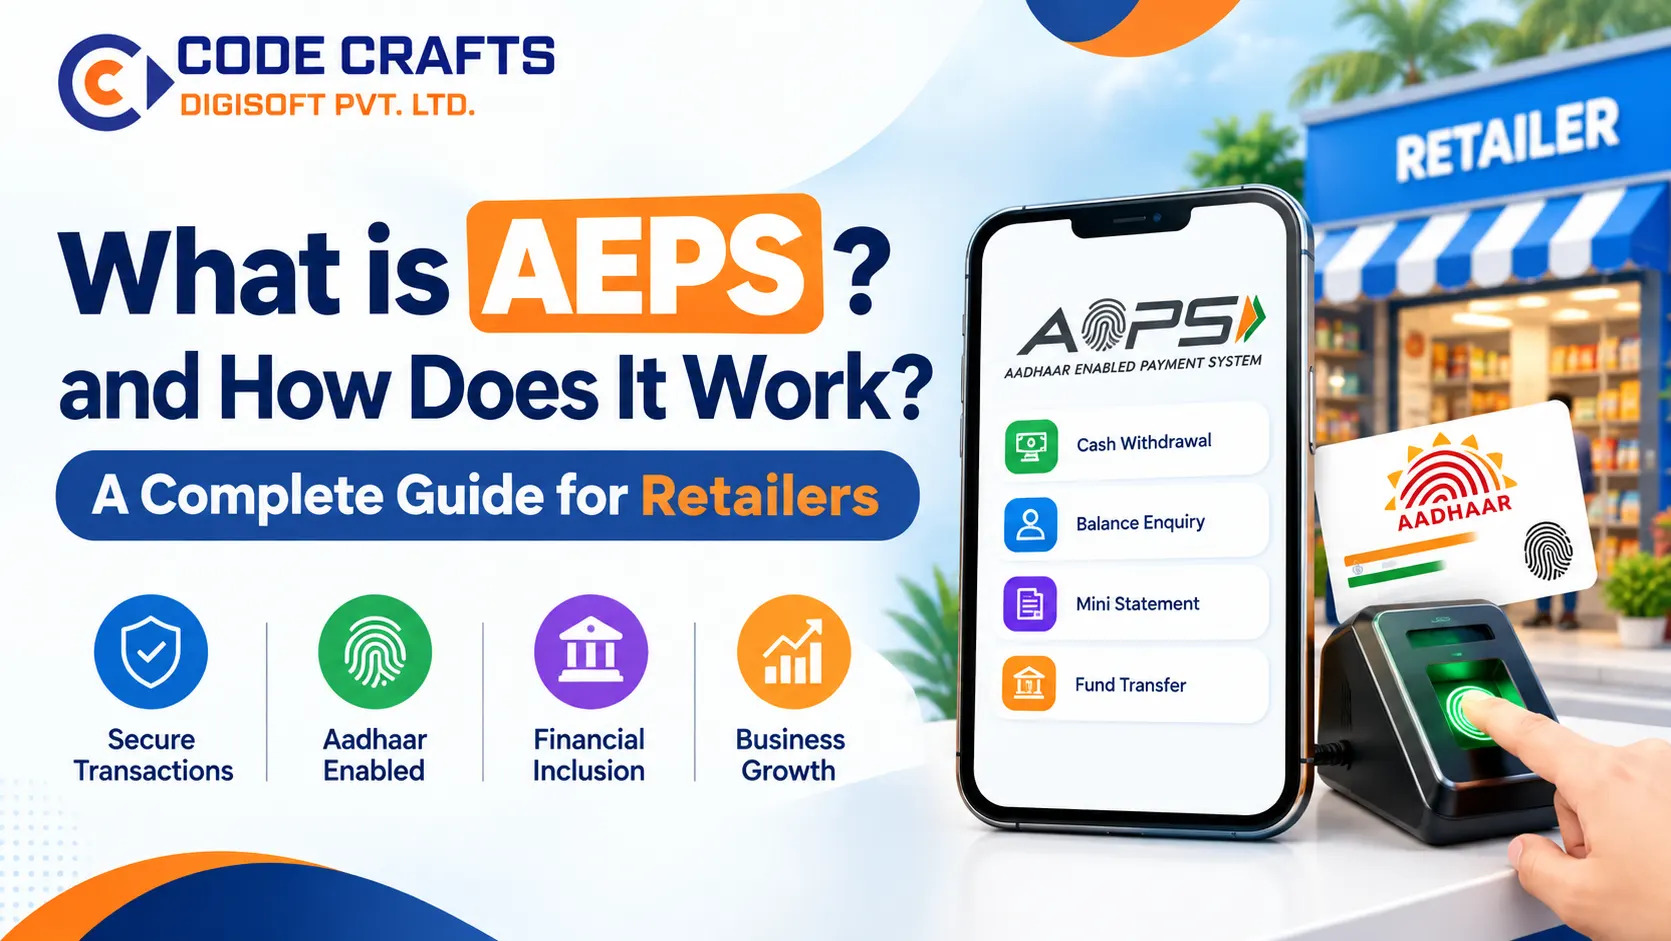
Imagine living in a village where the nearest bank branch is miles away by bus. It took almost half a day even to get some thousands of rupees from the bank. However, thanks to AEPS, things have changed now. One can easily visit the nearest shop, place his/her fingerprint on the scanner and be back home with the money in a few minutes.
It is also good for the shopkeepers because if you own a shop and wish to earn some extra income, then becoming an AEPS retailer is probably one of the easiest ways to do so. There is no need for any elaborate arrangement. Just a smartphone or computer, fingerprint scanner and AEPS service provider are all that is needed.
In this guide, we will look into what AEPS is, how it works, how to activate it, how to withdraw money using AEPS and how retailers earn commission. Also, there is a FAQ section towards the end that answers the frequently asked questions. We have tried our best to keep the language simple.
What Is AEPS?
AEPS is short for Aadhaar Enabled Payment System. In simple terms, it enables one to conduct basic banking transactions using the Aadhaar number and the fingerprint. AEPS is a product of NPCI or the National Payments Corporation of India, which is the same body that brought us UPI and RuPay.
There is no need for a debit card, a pin or internet banking. All that a customer does is walk into an AEPS retailer (also known as banking agents and business correspondents), give the Aadhaar number, select the bank and scan the finger. Once the system confirms that all is correct, the bank permits and the transaction is completed.
This is why AEPS is so important in villages and small towns. Many people there may have a bank account and Aadhaar card but not use cards and apps too much. For them, the local store becomes their bank.
Just one point to note here - the Aadhaar number should be linked to the bank account. Otherwise, AEPS will not work at all.
How Does AEPS Work?
On the surface, it all seems so simple, but there are a couple of systems working behind the scenes here. Let's trace the transaction through the process.
- The customer approaches the retailer and tells him/her how much cash they want.
- The retailer opens the AEPS app/portal and selects cash withdrawal.
- He/she enters the customer's Aadhaar number (Virtual ID) and selects the bank.
- The customer puts their finger on the biometric scanner.
- The request goes from the retailer's AEPS provider to NPCI, and further to the customer's bank where the fingerprint is matched against the Aadhaar database managed by UIDAI.
- If the fingerprint matches and there is sufficient balance, the bank approves the transaction and debits the account.
- The retailer gets a success message, gives cash and provides a receipt. If the customer's mobile number is registered, he/she receives an SMS too.
The entire transaction process takes less than a minute. For you as the retailer, the amount (plus your commission) is credited to your AEPS wallet. You provide the cash out of your pocket and later transfer the wallet balance to your bank account.
AEPS Services Your Customers Can Use
One objection, multiple banking facilities. Here are some of the things that your AEPS merchant will typically be able to do for his/her customers:
- Withdrawal of cash: the client withdraws money from their bank account.
- Deposit of cash: the client deposits cash in their bank account through you.
- Balance inquiry: an inquiry done in order to ascertain the amount in the client's bank account.
- Mini statement: the viewing of some recent transactions in the account.
- Fund transfer from Aadhaar to Aadhaar: the transfer of money from one bank account to another using only the receiver's Aadhaar number.
- Aadhaar Pay: a transaction where you pay someone through your fingerprint.
How to Activate AEPS
The answer depends on whether you're a customer or a retailer.
If you're a customer
- Usually, there is no need for any “activation.” If your Aadhaar is already registered with your bank account, AEPS will most probably work fine without fail. In case of verification and rectification of the link:
- Visit your nearest bank branch or use the app/ net banking/ATM to register your Aadhaar with your bank account.
- Ensure that your phone number on the account is updated to receive SMS notifications.
- Inquire about whether AEPS is enabled or not; some banks give you the option to enable or disable it through their app too.
If you're a retailer
You have to enroll with an AEPS service provider. The process is normally as follows:
- Select a trustworthy service provider with a definite commission structure and support system.
- Enroll yourself by providing your name, mobile number, and email.
- Do your KYC. Ensure that you have your Aadhaar card, PAN card, photograph, bank details, and proof of address of shop.
- Purchase a fingerprint scanner that is approved for use with Aadhaar.
- Get your biometric authentication done to make sure that your account is activated.
- Put some money in your wallet and execute your first transaction.
The processing time and documentation requirement may vary with each service provider, so be sure of all the things before paying any enrollment fees.
How to Withdraw Money from AEPS
Withdrawing money using AEPS is a fast process. This is what you will have to do as a customer:
- Make sure that you have your Aadhaar number (or Virtual ID) with you and it is linked to your bank account.
- Go to an AEPS merchant of your choice and request a cash withdrawal.
- Inform him about the amount you want to withdraw and your bank.
- Look at the screen and make sure that the Aadhaar number and amount are correct.
- Put your finger on the scanner when asked.
- Wait for the success message and then collect your money and the receipt.
- Check your SMS on the phone to make sure that the amount debited from your account is correct.
Two minor things to be aware of. Banks generally have a limit on every cash withdrawal done through AEPS and this limit is usually ₹10,000 per transaction, but this may differ from bank to bank. Also, ask the merchant whether there is any service charge before starting the process.
AEPS vs UPI: Are They the Same?
Short answer: no. Both are run by NPCI and both move money out of a bank account, so people often mix them up. But they work differently and suit different people.
| Point | AEPS | UPI |
| Full form | Aadhaar Enabled Payment System | Unified Payments Interface |
| How you prove who you are | Aadhaar number and fingerprint | UPI PIN |
| What the customer needs | Aadhaar linked to a bank account | Smartphone, UPI app and a bank account |
| Internet for the customer | Not needed (the retailer's device uses it) | Needed |
| Main use | Cash withdrawal and basic banking at a retailer | Instant online payments and transfers |
| Best suited for | Rural and semi-urban users | Anyone comfortable with a mobile app |
So if you have a smartphone and want to pay or send money digitally, UPI is perfect. If you want cash or basic banking without a card, a PIN or even a smartphone, AEPS is the better fit.
Benefits of AEPS for Retailers
Why should you introduce AEPS at your shop counter? Here are the main reasons:
- Additional earning: you receive an AEPS commission for each completed transaction, typically in relation to its value or on a flat slab basis.
- Increased footfall: the person coming to withdraw cash will most likely purchase something more from your shop before leaving.
- Minimal setup cost: basically, all you need is a device, a scanning machine and some cash and wallet balance.
- Trust in your local community: a trustworthy banking facility will bring customers to your shop again.
- Potential for expansion: most retailers also include money transfer, bill payments and micro ATMs as additional facilities in the same platform.
- The commission varies depending on where you are located. It will depend on your service provider, the type of service and the transaction value. Before joining, request the complete commission structure in writing.
- Practical advice: Cash Management. The cash is handed over first and the wallet gets credited later, so make sure you have enough cash and wallet balance. Being short in cash before a waiting customer is not a good image for a new facility.
AEPS Safety Tips and Common Mistakes
Using AEPS is safe when you follow a few easy steps. The following are some tips for the protection of customers and retailers alike:
- Do not disclose your Aadhaar number and fingerprints with people whom you do not trust.
- Whenever you are not making use of AEPS, set a biometric lock through UIDAI. You will be able to unlock it whenever you want to.
- Always ensure to confirm the amount before placing your fingers on the scanner.
- After each transaction, read the SMS. In case there is a unauthorized deduction, inform your bank immediately.
- Retailers should use certified fingerprint scanners and a registered AEPS service provider.
- Your device and app should always be updated. You should never keep your login open for anyone.
- Be cautious of those who ask for a large joining fee and promise large profits. Ask for their reviews and any evidence of profits.
The most frequent errors made are those of typing your Aadhaar number incorrectly, selecting a wrong bank and repeatedly scanning your finger even if it is unsuccessful. And in case you make a transaction and fail, but get debited, banks usually revert it to your account. If it does not reach within time,
About Code crafts Digisoft Pvt. Ltd.
Code crafts Digisoft Pvt. Ltd is a fintech company specializing in software development. Based in Jaipur, Rajasthan, the company has over 5 years of experience in building digital products that offer scalability and security features to help your startup or business grow.
- Are you an online retailer or distributor or a reseller looking to venture into the area of fintech? Our fintech solutions include the following platforms:
- AEPS platform which provides services such as cash withdrawal and balance inquiry among other banking services using the Aadhaar number.
- Quick Money transfer platform known as DMT (Domestic Money Transfer) to transfer money instantly for your customers.
- Provides services for micro ATM where banking services can be carried out by card.
- Digital wallet to be used for payments and transactions.
- Multi-level B2B, B2C and Reseller portal where commission management facilities are available.
In addition to providing fintech solutions, the company also develops website and app, custom software as well as digital marketing. The company highly emphasizes on bank-grade security, usability dashboard, and 24*7 technical support.
Conclusion
One of the easiest ways to make banking available to individuals living away from the bank branches is AEPS. It can be a profitable business for anyone who owns a store. All that customers require is to have their Aadhaar number associated with their bank accounts and a finger print. Retailers need to have an approved scanner, a trusted AEPS service provider, and a history of doing business with integrity.
If you wish to start an AEPS retailer business or create your own AEPS platform through AEPS API, choose a partner that provides you with secure software, clear commission scheme and timely customer support. Code crafts Digisoft develops fintech solutions such as AEPS, DMT, micro ATM, and digital wallet platforms for retailers, distributors and resellers.
Tags:
what is AEPS
Aadhaar Enabled Payment System
how does AEPS work
AEPS retailer
AEPS services
Frequently Asked Questions
About Author
Codecrafts Digisoft
Expert content creator and technology enthusiast at Code crafts Digisoft Pvt. Ltd.